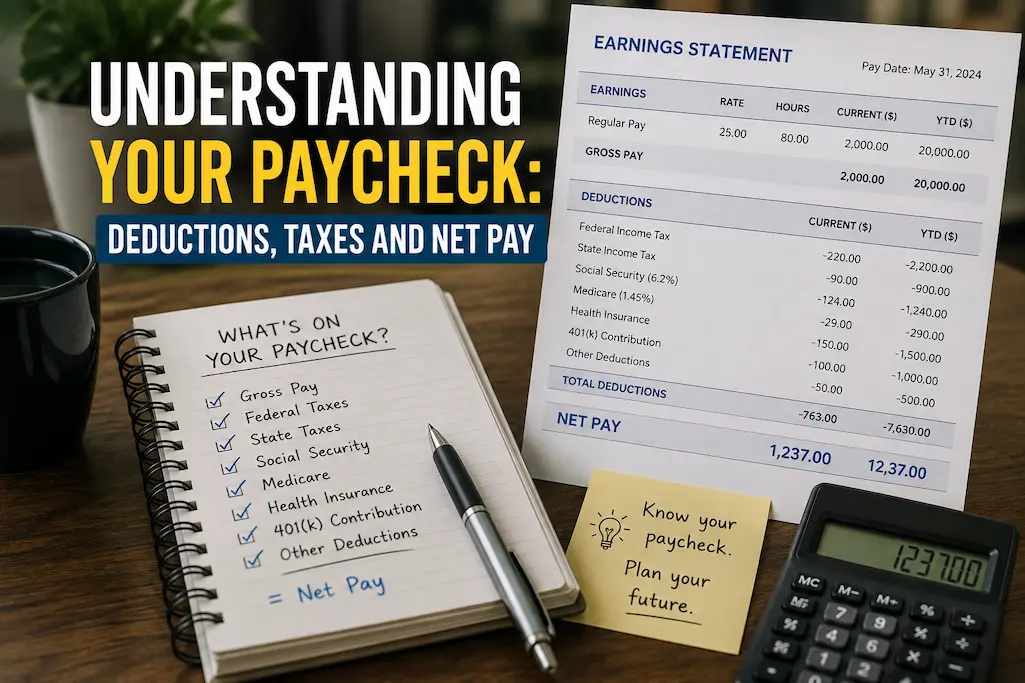

Your salary is not necessarily the amount of money you will see in your bank account each payday. If your job pays $5,000 a month before deductions, your actual deposit may be considerably lower because your paycheck can include federal and state taxes, Social Security, Medicare, health insurance, retirement contributions, and other deductions.
That difference can be confusing, particularly when you start a new job or notice that your take-home pay changed unexpectedly. The good news is that a paycheck is usually easier to understand once you stop looking at the final deposit as one unexplained number. Each major section tells you something about how your earnings were calculated, what was withheld for taxes, what you chose to pay for benefits or savings, and what remained available to you.
If you know how to read those sections, you can catch payroll mistakes sooner, understand your real income for budgeting purposes, and make more informed decisions about benefits and tax withholding.
Start With Gross Pay, Not Your Bank Deposit
The easiest place to start is gross pay.
Gross pay is what you earned for the pay period before employee taxes and other deductions are taken out. For a salaried worker, it may represent a portion of the annual salary. For an hourly worker, it may be based on the hours worked multiplied by the applicable rate, with overtime or other compensation potentially added.
Your gross pay can therefore change even when your basic hourly rate or annual salary has not changed.
For example, an hourly employee who normally works 40 hours each week may have higher gross pay in a pay period that includes overtime. A salaried employee might receive additional compensation from a bonus or other payment. Paid leave, commissions, and certain taxable benefits can also affect payroll calculations.
This is why the first question to ask when checking a paycheck is not, “Why is my deposit different?” It is, “Is my gross pay what I expected?”
If gross pay is already different from what you expected, the explanation may have nothing to do with taxes.
Then Find Your Net Pay
Net pay is the amount left after applicable taxes and other deductions have been taken from your earnings. It is the figure most closely connected to the money you actually receive.
A simplified version is:
Gross pay − taxes − other deductions = net pay
Suppose your gross pay for a paycheck is $2,500. You might see several hundred dollars going toward taxes and another amount going toward health insurance or retirement savings. The remaining amount becomes your net pay.
This is the number that usually matters most when you are building a household spending plan.
However, net pay should not be confused with the total value of your compensation. An employer may contribute toward health insurance or a retirement plan, for example, without that money appearing in your checking account. Your paycheck is therefore a record of your current earnings and deductions, not necessarily a complete summary of everything your employer provides.
What the Tax Lines Actually Mean
The tax section is where many people become confused because several different taxes can appear next to one another.
For a typical U.S. employee, the major federal payroll-related lines may include federal income tax, Social Security, and Medicare. State and local income taxes may also appear depending on where you live and work.
These taxes do not all work in the same way.
| Paycheck line | What it generally represents |
|---|---|
| Federal income tax | Federal income tax withheld from your wages |
| Social Security | Employee Social Security payroll tax |
| Medicare | Employee Medicare payroll tax |
| State income tax | State income tax withholding, where applicable |
| Local income tax | Certain local or municipal taxes, where applicable |
The exact lines on a paycheck vary by employer and location. Some workers will have deductions that others do not have.
The important point is that “taxes” are not one single deduction. Each line has a different purpose and calculation.
Federal Income Tax Is Withheld, Not Simply “Taken Because You Owe It”
Federal income tax withholding is one of the most misunderstood parts of a paycheck.
Your employer generally withholds federal income tax from your wages and sends that money to the government on your behalf. The amount withheld is influenced by your wages and the information provided on your Form W-4.
That withholding is not necessarily the exact amount of federal income tax you will ultimately owe for the year.
Your final tax liability is determined when you file your tax return based on the tax rules and circumstances that apply to you. The federal income tax already withheld from your paychecks is then taken into account.
This explains why two employees with similar salaries can have different federal income tax withholding.
It also explains why receiving a tax refund does not necessarily mean your employer “gave you extra money.” A refund can occur when the amount you paid through withholding during the year exceeds your final tax liability.
Your W-4 Can Affect Your Take-Home Pay
When you begin employment, you generally complete Form W-4. The information on that form helps your employer determine how much federal income tax to withhold from your paycheck. It can include information about filing status, multiple jobs, credits, other income, and deductions.
This matters because a change in your financial or household circumstances can affect whether your current withholding still makes sense.
For example, your situation may change after starting another job, experiencing a significant income change, getting married, or having other circumstances that affect your expected tax position.
The IRS provides a Tax Withholding Estimator that employees can use to review their withholding. If you determine that your withholding should change, the usual method is to submit an updated Form W-4 to your employer.
The important distinction is that changing your W-4 generally changes when and how much federal income tax is withheld from your paycheck. It does not magically eliminate tax that you actually owe.
Social Security and Medicare Are Different From Federal Income Tax
You may notice that Social Security and Medicare appear separately from federal income tax.
These are payroll taxes under the Federal Insurance Contributions Act, commonly called FICA.
For 2026, the employee Social Security rate is 6.2%, while the employee Medicare rate is 1.45%. Social Security has a 2026 wage base limit of $184,500, while Medicare has no wage base limit. An additional 0.9% Medicare tax withholding can apply to wages above $200,000 paid by an employer during the year.
You do not normally need to calculate these figures manually every payday. Your employer’s payroll system handles the withholding.
What is useful is understanding why these lines exist and recognizing that they are separate from federal income tax withholding.
Not Everything Under Gross Pay Is a Tax
This is one of the most useful distinctions to learn.
A paycheck may contain several deductions that are not taxes at all.
Depending on your employer and benefits package, you might see deductions for:
- Health insurance
- Dental insurance
- Vision insurance
- Retirement contributions
- Health savings accounts
- Flexible spending accounts
- Supplemental insurance
- Other employer-sponsored benefits
- Certain legally required deductions
These deductions can have different tax treatment, so you should not assume that every item reduces your taxable income in exactly the same way.
For example, a retirement contribution and a Medicare tax deduction serve completely different purposes. One may direct part of your compensation into a retirement account, while the other is a payroll tax.
That distinction becomes particularly important when you are trying to understand why your paycheck is smaller than your gross earnings.
A Paycheck Example Makes the Difference Clear
Imagine that an employee earns $3,000 in gross pay during one pay period.
Their hypothetical paycheck might look something like this:
| Item | Example amount |
|---|---|
| Gross pay | $3,000.00 |
| Federal income tax withholding | $320.00 |
| Social Security | $186.00 |
| Medicare | $43.50 |
| State income tax | $120.00 |
| Health insurance | $150.00 |
| Retirement contribution | $150.00 |
| Net pay | $2,030.50 |
This is only an illustration. Actual federal withholding, state taxes, benefits, and retirement contributions depend on the employee’s circumstances and payroll arrangements.
But the example shows something important.
The employee did not “lose” $969.50 to taxes. Some of that amount went toward federal and state taxes, some toward Social Security and Medicare, and some toward benefits and retirement savings.
Looking at the deductions individually gives you a much better explanation of where the difference went.
Why Your Take-Home Pay Can Change
A common mistake is assuming that a different bank deposit automatically means your employer changed your salary.
There are many other possibilities.
Your gross pay could have changed because you worked different hours, received overtime, earned a commission, received a bonus, or took unpaid time away from work.
Your deductions could also have changed. A health insurance premium might change after a benefits update. A retirement contribution percentage might have been modified. A deduction may have reached an annual limit or started appearing after a new enrollment.
Tax withholding can change as well.
The fastest way to investigate a surprising paycheck is therefore to compare the current pay stub with the previous one, rather than looking only at the final deposit.
Current Pay and Year-to-Date Numbers Are Not the Same
Most pay stubs contain both current-period amounts and year-to-date, or YTD, amounts.
Current-period figures relate to the paycheck you are looking at. YTD figures accumulate amounts from earlier pay periods during the year.
Imagine your paycheck shows:
Social Security — Current: $186
Social Security — YTD: $2,046
The $186 is associated with the current paycheck. The $2,046 represents the accumulated amount for the year so far.
The same distinction may appear for federal income tax, Medicare, retirement contributions, and other items.
This is easy to overlook when you first start reading a pay stub, particularly if the YTD numbers are much larger than the current-period amounts.
What to Check When Your Paycheck Looks Wrong
If your paycheck is unexpectedly different, work through the numbers in order rather than immediately assuming there is a tax problem.
1. Check the pay period.
Make sure you are looking at the correct paycheck and pay dates.
2. Check your hours or salary.
If you are paid hourly, confirm the hours and overtime. If you are salaried, confirm the expected salary amount.
3. Check gross pay.
Compare it with your previous paycheck and your employment terms.
4. Compare the tax lines.
Look for changes in federal, state, local, Social Security, or Medicare withholding.
5. Review other deductions.
Check insurance, retirement contributions, and other benefit deductions.
6. Check year-to-date figures.
Make sure you are not accidentally comparing a YTD amount with a current-pay amount.
7. Compare the net pay with your bank deposit.
The deposit should generally correspond to the net amount after considering any separate payroll arrangements.
If you still cannot explain the difference, ask your employer’s payroll or human resources department to explain the specific line that changed.
Your Net Pay Is Usually the Better Starting Point for a Budget
When people create a budget using their annual salary, they can easily overestimate how much money is available for everyday expenses.
Suppose you earn $60,000 a year. Dividing that number by 12 gives you $5,000 per month before deductions. That does not mean you have $5,000 available to spend.
Your actual take-home amount depends on taxes, benefits, retirement contributions, and other deductions.
For regular household budgeting, net pay is therefore usually the more useful starting point.
You can still use gross income when comparing job offers, considering total compensation, or evaluating certain financial requirements. But your grocery budget, rent payment, savings transfer, and other recurring expenses ultimately have to fit within the money that actually becomes available to you.
A Lower Paycheck Does Not Always Mean You Are Worse Off
This is another point worth considering when reviewing deductions.
Imagine your take-home pay decreases because you increased your workplace retirement contribution.
Your checking account receives less money, but the entire difference did not disappear. Part of your compensation is now being directed somewhere else.
The same idea can apply to certain insurance deductions. Paying for health coverage reduces your paycheck, but you are receiving coverage in return.
This does not mean every deduction is automatically worthwhile. Benefits have costs, and employees should understand what they are paying for. The useful question is not simply, “How do I make my paycheck bigger?”
It is:
“What am I receiving in exchange for each deduction, and does it fit my financial priorities?”
That is a much more useful way to evaluate a paycheck.
When You Should Review Your Withholding
You do not need to change your W-4 every time your paycheck moves by a few dollars.
However, a significant change in your financial circumstances can be a good reason to review your withholding.
For example, you might want to check it after:
- Starting or leaving a job
- Taking on another job
- Experiencing a substantial income change
- Getting married or divorced
- Experiencing another major household change
- Discovering that your withholding is consistently far from your expected tax position
The IRS recommends periodically checking withholding, and its withholding tools can help employees estimate whether their current withholding is appropriate.
If the issue is significant or complicated, professional tax advice may be more appropriate than trying to adjust payroll deductions based on a guess.
The Five Numbers Worth Knowing on Every Paycheck
You do not have to become a payroll expert to understand your earnings.
At a minimum, know these five things:
| Number | Why it matters |
|---|---|
| Gross pay | What you earned before deductions |
| Federal income tax | Federal income tax withheld |
| Payroll taxes | Social Security and Medicare amounts |
| Other deductions | Benefits, retirement, and other deductions |
| Net pay | What remains after the listed deductions |
Once you can identify those numbers, most paychecks become much easier to interpret.
You can then investigate individual deductions only when something changes or you need more information.
Make Your Paycheck Part of Your Financial Routine
A paycheck should not be something you glance at only when the deposit appears in your bank account.
Take a minute to review it regularly. Confirm that your pay is correct, watch for unexpected deductions, and pay attention to year-to-date amounts. If your circumstances change, consider whether your benefits and tax withholding still reflect your situation.
Most importantly, use your net pay when deciding what you can realistically spend and save.
Understanding your paycheck will not necessarily increase your income, but it can eliminate a lot of confusion around where that income goes. Once gross pay, taxes, withholding, benefits, retirement contributions, and net pay are no longer just unexplained lines on a screen, your paycheck becomes a useful financial tool rather than a document you simply file away.
Note: This article provides general U.S. financial and payroll education. Federal, state, and local tax rules can vary, and individual tax situations can be more complicated than the examples shown here. For questions about your specific tax liability or payroll situation, consider using official IRS resources or speaking with a qualified tax professional.
Ethan Walker is a personal finance writer who focuses on helping beginners understand money simply and practically. He writes about budgeting, saving money, financial literacy, and side hustles with the goal of making financial education easier and more approachable. His content is designed to help readers build better financial habits and make smarter everyday money decisions.