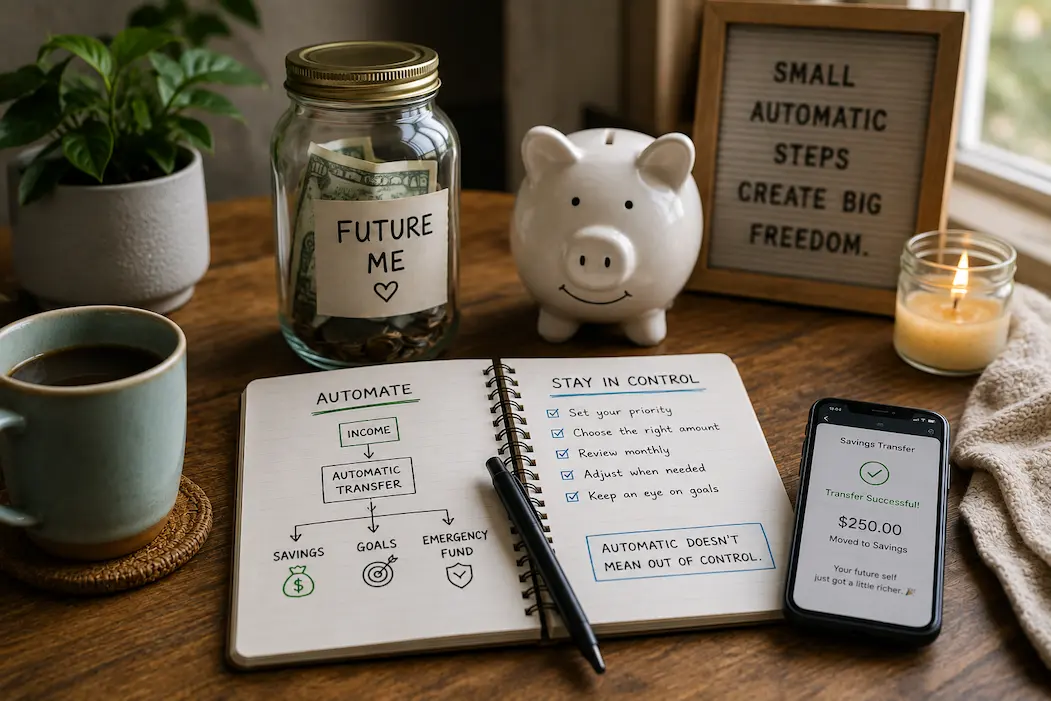

Automated saving can eliminate one of your daily decision-making tasks and significantly simplify the saving process. Instead of waiting until the end of the month to check your balance, you can set up regular transfers to deposit specific amounts into your savings account. However, the problem is that automated saving can also create financial friction if the transfer amount does not align with your actual income and expenses.
What appears to be a small transfer on paper can become problematic if bills arrive early, your income changes, or you face multiple unexpected expenses in a single month. In such cases, automated saving ceases to be a useful mechanism and instead becomes a financial burden requiring extra management.
The key, therefore, is not to automate as much as possible but to establish an amount and a transfer schedule that align with your actual cash flow while maintaining enough insight and flexibility to make adjustments when circumstances change. When used correctly, automated saving should complement your budget, not conflict with it.
Understanding the True Power of Automated Saving
Automated saving is essentially a method of transferring money from one account to another according to a preset schedule. Depending on your bank and account settings, this could mean regularly moving money from your everyday accounts to your savings account or utilizing other automated saving features offered by your bank.
Importantly, automation does not make your money grow; it changes when and how you spend it. If you save €150 a month, your daily spending will decrease by €150. While this change is certainly positive—ensuring that saving has a place in your budget—you still need to account for these savings alongside your spending on bills, groceries, transportation, and other expenses. That is why it is best to use automatic saving in conjunction with a budget, rather than replacing it. Before deciding how much you can safely transfer, you must first determine what your account needs to cover.
Automation Should Follow Your Cash Flow
Consider someone who receives €2,400 near the beginning of each month and has predictable essential expenses of approximately €1,700. An automatic transfer of €200 might fit comfortably if the remaining money also covers their normal flexible spending and irregular costs.
But someone with the same income could have an entirely unique cash-flow pattern. Perhaps several bills come due during the first week, while other expenses occur throughout the month. In that case, the timing of the transfer matters almost as much as the amount.
A good automated savings system therefore starts with the question:
“When can I move this money without making the rest of the month unnecessarily difficult?”
That is a more useful question than simply asking how much you would like to save.
Choose an Amount That Leaves Room for Real Life
One of the most common mistakes with automatic savings is choosing an ambitious amount based on an ideal month. An ideal month might have no unexpected purchases, no unusually high utility bill, no annual renewal, no repair, and no social event that costs more than expected. Real months are rarely that clean.
Start with an amount that you can reasonably maintain after accounting for your normal obligations and less predictable expenses. If €100 per month is sustainable while €250 repeatedly forces you to transfer money back, the smaller amount may be the better system. Consistency matters because a savings system that works for twelve months is more useful than one that looks impressive for six weeks and then has to be abandoned. You can always increase the transfer later after observing your actual cash flow.
Keep a Buffer in Your Everyday Account
Automation becomes much safer when you avoid treating every euro left after the transfer as immediately available for spending. A small cash buffer in your everyday account can help absorb timing differences between income, bills, and purchases. The appropriate amount depends on your circumstances, income stability, payment schedule, and account requirements.
For example, suppose you normally keep €500 available after your regular monthly expenses. If an automatic savings transfer leaves only €100 of apparent flexibility, a single unexpected bill could create a problem even though your monthly budget looked reasonable.
A buffer gives you breathing room. It also helps separate two different concepts: money intended for savings and money needed to keep your everyday cash flow stable. Moving every possible euro into savings is not necessarily efficient if you repeatedly have to move it back.
Pick the Right Transfer Date
The date of an automatic transfer can make a surprisingly large difference. If your income arrives on a predictable date, transferring money shortly afterward can work well because you know what funds have entered the account. However, the best date depends on when your major payments leave the account. Someone who pays monthly may find that a transfer shortly after payday works well. Someone paid weekly or with variable income may need a different arrangement.
Review your account for at least one or two normal payment cycles. Identify when income arrives, when large bills are withdrawn, and when your account balance tends to be lowest. Then place the savings transfer at a point that does not unnecessarily squeeze the account. The goal is not simply to move money quickly. It is to create a predictable rhythm that matches your actual financial calendar.
Do Not Confuse Savings Automation With a Locked Budget
An automatic transfer should not make you afraid to adjust your finances. If your circumstances change, the amount may need to change too. A temporary reduction can be more sensible than repeatedly overdrawing an account or relying on credit to cover ordinary expenses.
For example, suppose you normally save €200 each month but face a temporary increase in essential expenses. Reducing the transfer to €100 for several months does not mean the savings plan has failed. It means the plan has responded to reality. Likewise, if your expenses fall and you consistently have more available cash, you may decide to increase the transfer. Automation should remove unnecessary decisions—not remove your ability to make choices.
Use Different Savings Accounts for Different Purposes
Another way to maintain control is to avoid putting every savings goal into one indistinguishable balance.
You might have separate goals for:
- An emergency reserve
- A planned large purchase
- Annual or irregular expenses
- Travel or another discretionary goal
- A longer-term financial objective
The exact structure depends on your banking options and personal situation, but separating purposes can make automated saving easier to understand. Suppose you automatically transfer €250 each month into one savings account. Six months later, the balance may look encouraging, but you may not know how much is actually available for a planned purchase and how much you mentally consider reserved for emergencies. Assigning money to specific purposes can reduce that confusion.
Automate the Transfer, Not the Decision to Spend
Automation works best when it is used to support a deliberate savings decision. It should not become an excuse to stop checking your financial situation. Please review your automatic transfers periodically and consider the following questions:
- Is the amount still affordable?
- Is the money going toward the goal I originally intended?
- Does the transfer still fit my income and expenses?
- Am I regularly moving money back because the transfer is too large or poorly timed?
These questions take only a few minutes, but they help prevent an old financial arrangement from continuing long after your circumstances have changed.
Watch for Signs That Your Automatic Savings Is Too Aggressive
Your savings transfer may need adjustment if you regularly experience problems such as:
- Running short of money before your next income payment
- Moving savings back into your everyday account
- Relying on credit to cover ordinary expenses
- Delaying necessary bills because money was transferred too early
- Paying avoidable account or overdraft fees
- Frequently changing the transfer amount because the original figure is unrealistic
One isolated problem does not necessarily mean the entire system is wrong. But repeated problems are useful evidence. If you regularly save €300 and repeatedly withdraw €150 of it again, the headline savings amount is misleading. Your effective savings may be much lower, while the extra transfers create unnecessary account movement. A sustainable €150 transfer may produce a better result.
Build Automation Around Your Irregular Expenses
Monthly savings can sometimes fail because a budget ignores expenses that occur less frequently. Imagine that your regular monthly expenses are comfortably covered, but you know that insurance, annual memberships, school costs, maintenance, gifts, or other irregular expenses will arrive during the year. If you automate savings without accounting for these costs, you may unintentionally treat money needed for future bills as available for another goal. One solution is to create a separate sinking-fund-style category for known irregular expenses. Instead of allowing these bills to surprise you, estimate their annual cost and set aside money gradually.
For example:
| Irregular expense | Estimated yearly cost | Monthly amount |
|---|---|---|
| Insurance | €600 | €50 |
| Annual membership | €120 | €10 |
| Home maintenance | €360 | €30 |
| Gifts and occasions | €240 | €20 |
| Total | €1,320 | €110 |
The €110 is not necessarily “savings” in the same sense as money being built for long-term wealth. It is money being reserved for predictable future spending.
That distinction is important because otherwise you may overestimate how much of your automated savings is truly available for your main goal.
Make It Easy to See What You Are Saving
Automation can become invisible, and invisibility is not always helpful. If money leaves your everyday account automatically every month, you may eventually stop noticing the transfer altogether. This can help form habits, but you should still know how much you are saving and what the money is for.
A simple monthly review can show:
| Item | Amount |
|---|---|
| Planned automatic savings | €200 |
| Additional manual savings | €50 |
| Money moved back | €0 |
| Net savings for month | €250 |
You do not need to create a complicated financial dashboard. A basic record is enough to answer an important question: Is the system actually increasing your savings balance?
If the answer is consistently yes, the automation is doing its job.
What to Do When Your Income Changes
Automatic savings requires more attention when income is irregular. If you earn different amounts from month to month, a fixed transfer may be inappropriate if it assumes that every month will resemble the best month. A percentage-based approach may sometimes fit variable income better, while a smaller fixed amount can provide a predictable minimum.
For example, someone whose monthly income ranges from €1,800 to €2,600 might choose a conservative fixed transfer that remains manageable during lower-income months. In stronger months, they could make an additional voluntary contribution after essential expenses and planned irregular costs are covered. There is no single correct formula. The important principle is to avoid building an automatic commitment around income that is not reliably available.
Know When to Pause or Reduce the Transfer
There are situations where saving aggressively may not be the immediate priority. If your essential bills are becoming difficult to cover, your income has fallen, or an urgent financial obligation has appeared, temporarily reducing an automatic transfer can be reasonable.
This is particularly important when continuing the transfer would force you to borrow money for ordinary expenses. Moving €200 into savings while simultaneously carrying new high-cost debt to pay for necessities does not automatically represent financial progress. Your savings system should serve your broader financial situation, not operate independently from it. When circumstances improve, you can review the transfer and decide whether to restore or increase it.
A Practical Automatic-Savings Setup
If you want a simple starting system, use the following process.
- First, review your normal cash flow. Identify income dates, major bills, flexible spending, and irregular expenses.
- Next, choose a conservative transfer. Start with an amount that leaves enough room for ordinary fluctuations rather than using your theoretical maximum.
- Then, choose a sensible date. Schedule the transfer around your income and major payment dates.
- Keep an everyday buffer. Do not assume that every remaining euro should be moved elsewhere.
- Give the savings a purpose. Know whether the money is for emergencies, a planned purchase, irregular expenses, or another goal.
- Review the system periodically. Increase, reduce, or pause the transfer when your financial circumstances change.
This creates automation without surrendering control.
A Quick Check Before Increasing Your Automatic Savings
Before raising your monthly transfer, ask yourself five questions:
- Have my essential expenses been covered comfortably?
- Have I accounted for irregular costs coming up?
- Am I keeping a reasonable cash buffer?
- Have I avoided regularly moving previous savings back?
- Can I maintain the higher amount without relying on credit?
If the answer to most of these questions is yes, increasing the transfer may be reasonable. If several answers are no, fixing the underlying cash-flow problem may be more useful than simply transferring more money.
Conclusion
Automated saving can make your savings more stable, but do not confuse automation with financial control. Even with automated transfers, it remains part of your budget and must be aligned with your income, expenses, and any unexpected costs throughout the year. The safest approach is not necessarily the most effective one; rather, the best approach is one you can easily maintain without frequent adjustments, reliance on credit, or struggling to make ends meet.
Start with reasonable amounts, pay attention to transfer dates, establish a daily buffer, and—if applicable—set multiple savings goals. Review your account regularly to account for changes in your circumstances. In this way, automation becomes a tool to support your financial decisions rather than a rigid rule that dictates them.
FAQs
1. Automated saving versus manual saving?
Automated saving can make your savings more stable because transfers happen automatically, meaning you don’t have to make a new decision each time. However, automation isn’t for everyone. The amount and timing still need to align with your cash flow, and you must continuously review the automated transfer arrangement based on changes in your circumstances.
2. How much should I save automatically each month?
There is no fixed amount that works for everyone. Start by choosing a reasonable amount, taking into account your basic living expenses, one-off costs, and a small buffer. A lower amount that you can save consistently is likely more valuable than putting yourself under pressure with frequent transfers.
3. What if I want to move money back from my savings?
If such an event happens only occasionally, it can be treated as a one-off expense. If it happens frequently, please review the amount and timing of the automated transfers. If you frequently make transfers, such behaviour could indicate that the transferred amount exceeds your current budget.
4. Should I set up automatic savings to occur immediately after receiving my salary?
This works well for people with a stable income, as the funds are deposited into the account beforehand. However, the best timing depends on when your bills and other expenses are debited from your account. It is not advisable to schedule it too early; this avoids putting unnecessary pressure on your employer when major payments are being processed.
5. Can I adjust the automatic savings amount later?
Different banks or financial institutions use different methods for modifying recurring transfers, but generally, you can adjust the amount. If your income or expenses change and you need to adjust the amount, this is not a system error. Flexibility is one of the key factors in the long-term success of an automatic savings plan.
Ethan Walker is a personal finance writer who focuses on helping beginners understand money simply and practically. He writes about budgeting, saving money, financial literacy, and side hustles with the goal of making financial education easier and more approachable. His content is designed to help readers build better financial habits and make smarter everyday money decisions.