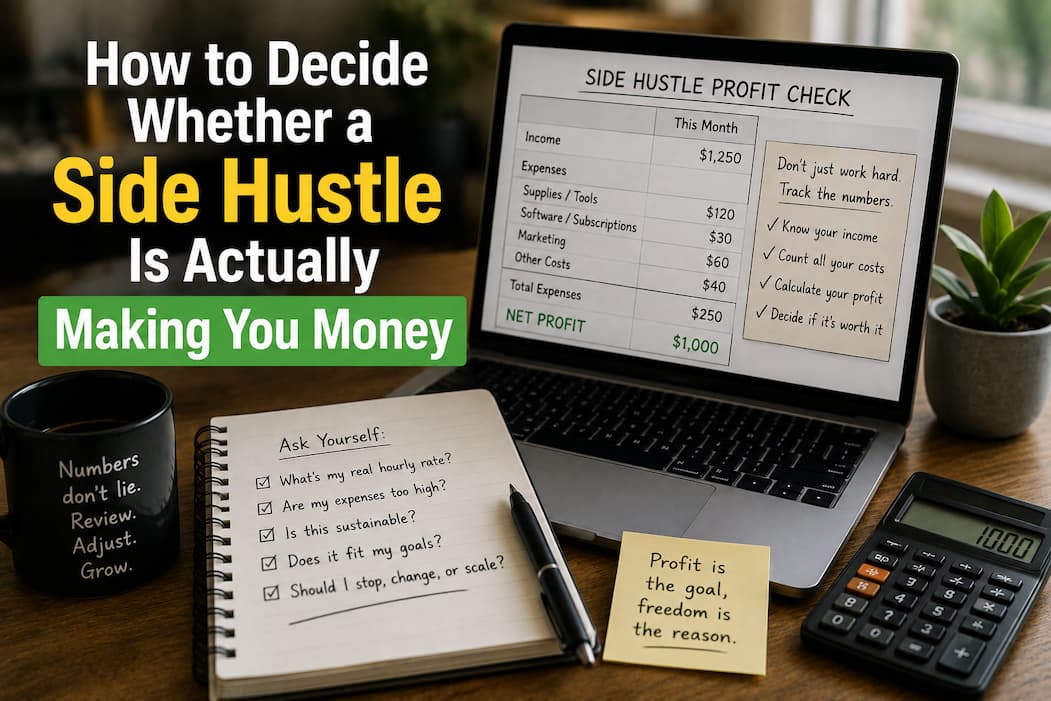

A side hustle can look profitable long before it actually is. Seeing money arrive in a bank account, receiving several customer payments, or ending a month with more cash than you started with can create the impression that the work is paying off. But revenue is not profit, and profit is not a worthwhile use of your time. A side hustle can generate $1,000 in sales, but after you consider supplies, platform fees, transportation, taxes, refunds, and other costs, it leaves very little behind.
The better question is not simply, “How much did I make?” It is, “How much did I keep after the costs of earning it, and was that return worth the time and effort involved?” Looking at those numbers gives you a much clearer picture of whether to continue, change, or eventually scale the side hustle.
Start With Revenue, But Do Not Stop There
The easiest number to find is usually revenue. This is the total amount customers or clients paid you before subtracting the expenses associated with producing or delivering the work. If you sell $800 worth of handmade products, receive $600 from freelance projects, or earn $450 from local services during a month, those amounts are revenue rather than take-home profit.
Revenue is useful because it tells you whether people are actually paying for what you offer. A side hustle with no meaningful revenue has a different problem from one that generates consistent sales but has high costs. However, revenue alone can make an unprofitable activity look successful. A seller may collect $2,000 from customers while spending $1,400 on inventory, shipping, marketplace fees, packaging, advertising, and other direct costs. The $2,000 figure sounds impressive until you examine the remaining amount.
It also helps to separate money received from money earned. A client might pay an invoice at the end of one month for work completed during the previous month. Similarly, a customer could place an order and later request a refund. Keeping basic records of sales, expenses, refunds, and outstanding payments prevents a single bank transaction from giving you a misleading picture of how the business is performing.
Calculate What the Side Hustle Costs You
Once you know your revenue, please list the costs required to generate it. Some are obvious, such as materials purchased for an order, delivery charges, marketplace commissions, or advertising expenses. Others are easier to overlook because they are mixed into ordinary household or business spending.
For example, someone who provides local services may spend money on fuel, parking, equipment, cleaning supplies, software, insurance, or replacement tools. Someone working online might pay for website hosting, software subscriptions, payment processing, advertising, stock assets, or freelance assistance. The exact expenses depend on the type of side hustle, so there is no universal percentage that can be applied to every activity.
A useful starting point is to divide expenses into direct costs and overhead. A particular sale or job is closely connected to direct costs. Overhead supports the side hustle more generally, such as software or website costs. You do not necessarily need an elaborate accounting system when the activity is small, but you do need enough records to avoid confusing sales with actual earnings.
Do Not Forget the Small Expenses
Small costs deserve attention because they can accumulate without being obvious individually. A $15 subscription may seem insignificant. So might several delivery trips, a few payment-processing charges, packaging purchases, or occasional promotional expenses. When the side hustle is small, these costs can consume a surprisingly large share of the money it generates.
That does not mean every expense must be eliminated. Some expenses are necessary to provide a service or make the activity more efficient. The important point is to know what you are paying for and whether the expense provides enough value to justify itself.
A simple monthly record can include revenue, direct expenses, overhead, refunds, and other business-related costs. Reviewing the list regularly can reveal expenses that seemed harmless when considered separately but become meaningful when viewed over several months.
Measure Profit Instead of Just Sales
After identifying revenue and expenses, calculate the amount left over.
Profit = Revenue − Business Expenses
Suppose a side hustle generates $900 during a month. You spend $250 on materials, $80 on platform and payment fees, $70 on transportation, and $50 on advertising. Your illustrative operating profit would be
$900 − $250 − $80 − $70 − $50 = $450
That $450 is much more useful than the original $900 when you are deciding whether the activity is financially worthwhile. However, it may still not represent what you ultimately keep. Depending on your circumstances and location, taxes and other obligations may also need to be considered.
This scenario is why a side hustle should ideally be evaluated using several numbers rather than one headline figure. Revenue tells you how much money came in. Expenses show what it cost to generate that money. Profit shows what remained before considering items that may sit outside the operating expenses you recorded.
Then Calculate Your Real Hourly Return
Profit becomes much more meaningful when you compare it with the time required to produce it.
Imagine two side hustles that each generate $500 of monthly profit. The first takes about 10 hours during the month. The second requires 40 hours. Financially, they produce the same monthly profit, but the return on your time is completely unique.
You can estimate an hourly return with a simple calculation:
Estimated hourly return = Profit ÷ Total hours spent
If you earn $500 of profit after spending 10 hours, the result is $50 per hour. If the same $500 requires 40 hours, the result is $12.50 per hour.
This calculation should include more than the time spent directly serving customers. Consider preparation, communication, purchasing supplies, traveling, administrative work, editing, posting listings, bookkeeping, and cleaning up afterward. A side hustle that looks efficient when you count only the visible work can look very different once you include the supporting tasks.
Include the Time You Normally Ignore
Administrative time is one of the easiest things for a side-hustle owner to underestimate. Answering messages for ten minutes may not feel like work. Neither does creating an invoice, researching a product, scheduling appointments, or driving to collect supplies. But those activities still consume hours that you could have spent elsewhere.
You do not need to track every second forever. A more practical approach is to measure your time for a representative period, such as several weeks, and use that information to estimate the normal workload. If the workload changes substantially from month to month, compare several periods rather than relying on one unusually busy or quiet week.
This also helps you identify opportunities to improve the business. If a large portion of your time is spent on tasks that produce little value, automation, better scheduling, clearer customer policies, or a different pricing structure may improve the economics without requiring you to work more hours.
Look at Cash Flow Separately From Profit
Profit and cash flow are related, but they answer different questions. Profit asks whether the activity generated more economic value than it consumed during a period. Cash flow asks when money actually moved in and out. A side hustle can appear profitable on paper while experiencing a temporary cash shortage because customers have not paid yet or because you had to purchase inventory before receiving sales revenue.
The reverse can happen too. You might receive a large payment in one month for work completed earlier, making your bank balance look unusually strong even though the underlying activity was not particularly profitable during that period.
For a small side hustle, a basic cash-flow record can be surprisingly useful. Track when customers pay and when you actually pay major expenses. This gives you a clearer picture of whether the side hustle can comfortably fund its costs rather than requiring repeated transfers from your personal account.
Watch for Costs That Grow Faster Than Revenue
A side hustle can become more popular without becoming more profitable. This happens when additional sales bring disproportionately higher expenses. Consider a product seller who doubles monthly sales but also needs significantly more inventory, packaging, advertising, delivery time, and customer support. Revenue has increased, but the additional work may not be producing much additional profit.
The same issue can appear in services. Taking on more clients may require longer working hours, more travel, additional software, subcontractors, or equipment. If each new customer adds nearly as much cost as revenue, growth by itself does not solve the problem.
One useful question is, “What happens to my profit when I add one more customer or job?” If the answer is consistently positive and the extra work remains manageable, the model may have room to grow. If each additional sale creates substantial complexity or expense, changing the pricing or delivery model may be more useful than simply chasing more volume.
Compare Good Months With Normal Months
A single unusually strong month can distort your judgment. Perhaps you received a large one-time project, sold an expensive item, or had an unusually busy holiday period. That result is encouraging, but it does not necessarily represent the normal economics of the side hustle.
Instead of asking whether you made money last month, search for a pattern across several months. Compare revenue, expenses, profit, hours worked, and the number of customers or projects completed.
A simple record might look like this:
| Month | Revenue | Expenses | Profit | Hours |
|---|---|---|---|---|
| January | $700 | $220 | $480 | 18 |
| February | $760 | $240 | $520 | 20 |
| March | $680 | $210 | $470 | 17 |
| April | $900 | $310 | $590 | 24 |
The figures above are illustrative rather than a prediction of what any particular side hustle should earn. The important pattern is that the owner can now compare profit with workload instead of looking only at sales.
If profit is reasonably consistent, that provides stronger evidence than one exceptional result. If profit swings widely, the next step is to understand why.
Check Whether You Are Underpricing Your Work
Sometimes a side business is indeed profitable, just not at the price you’re doing the labor for. This happens when people calculate their price based only on the cost of materials. Suppose a service uses $20 in resources and sells for $50. The $30 difference could seem tempting at first sight. But if the job takes two hours after prep, communication, travel and clean up, the economics aren’t that impressive.
The price should be based on the entire structure of the task and not just the most visible cost. That’s not a license to charge whatever you want or to assume that customers will accept any rise. It entails knowing the cost of delivering the product or service and whether the return is appropriate for the market and your situation.
If clients frequently baulk at increased pricing, it can be useful information, too. The remedy could be to simplify the service, cut expenses, improve the product, target another consumer group, or determine that the activity is better as an occasional project than a main source of income.
Separate Business Expenses From Personal Spending
Another red flag is consistently utilizing your own money to cover side-hustle expenses and failing to record those transactions properly. If you spend $300 from your personal account on activity expenses, but your side-hustle records only indicate $100 in expenses, then your reported profit will be deceiving.
Not every little activity needs separate accounts, but it is crucial to keep good records. Banking separately can also simplify recordkeeping, and depending on the type and scale of the activity, it can help segregate personal expenditures from company activities.
The important thing is to be consistent. Document your side hustle income, document your side hustle costs, and don’t judge the profitability of a single bank account. If money is going back and forth between your personal finances and the side hustle, make it clear that those are transfers and not sales or expenses.
Before You Call the Money “Yours,” Think
The leftover money after normal business expenses isn’t usually the amount you can comfortably consider personal spending money. Tax treatment depends on the activity, your overall income, deductions, and business structure and jurisdiction.
In the US, if you have a side business and you make money, there are federal tax ramifications in addition to just what you put in your bank account. State and local rules could also be affected. The specific treatment will depend on the person’s circumstances. A side-hustle profitability evaluation should not presume that each dollar of accounting profit becomes spendable cash.
One way to do this is to set aside the money you owe the government instead of spending all your business earnings as if they were personal income. If the activity grows significant or complex, professional tax counsel can be worthwhile. This is not a matter of trying to make a modest side hustle look like a big enterprise, but rather trying to prevent an apparently profitable activity from resulting in a nasty financial surprise later.
Let the Numbers Tell Us What Happens Next
After a few months of tracking the side hustle, the decision is easier. It might be worth it, give you a decent return on your time, and have upward potential. If so, it might make sense to continue it or slowly extend it.
Instead, you may find it makes money but pays poorly for your time. That does not mean you should just quit. You might increase rates where you can, discontinue unproductive services, cut unnecessary costs, streamline scheduling, or focus on the customers and goods that provide you with the best results.
There’s nothing wrong with concluding a side hustle that just isn’t worth maintaining. This choice can be a logical financial option if the occupation regularly earns little profit, takes a lot of time, requires constant personal subsidies, or causes more stress than the financial return is worth. A side hustle should be in service of your larger financial objectives, not an obligation since you’ve already put in time.
A Simple Side-Hustle Profitability Check
Before making a decision, review these questions:
- How much revenue did the side hustle generate?
- What did it cost to produce that revenue?
- What was left after those costs?
- How many hours did you actually spend on this?
- What was the approximate return per hour?
- Are the results consistent across several months?
- Are expenses rising faster than revenue?
- Are you relying on personal money to keep the activity running?
- Have you considered applicable taxes and other obligations?
- Is the return worth the time, effort, and risk involved?
The answers will usually tell you more than a revenue screenshot or a single good month ever could.
Profitability Is About More Than a Big Revenue Number
A side hustle doesn’t necessarily have to be highly profitable to be worthwhile. A small business with low overhead, a minimal time commitment, and steady profits can be more valuable than a large operation that requires constant investment and yields only a meager return after expenses.
That is why it is important to honestly assess the effectiveness of your side hustle. Track your income, record your expenses, measure your performance, and analyze the data over a period of several months. Then, adjust your strategy based on the metrics—not on how busy the side hustle makes you appear.
If your side hustle is truly profitable, you should see a significant return after expenses. If not, that doesn’t mean it’s a negative sign; the insight itself is valuable. Understanding where your money goes allows you to decide whether to adjust your pricing, cut costs, restructure the business, become more selective, or change the role the venture plays in your financial life.
Ethan Walker is a personal finance writer who focuses on helping beginners understand money simply and practically. He writes about budgeting, saving money, financial literacy, and side hustles with the goal of making financial education easier and more approachable. His content is designed to help readers build better financial habits and make smarter everyday money decisions.