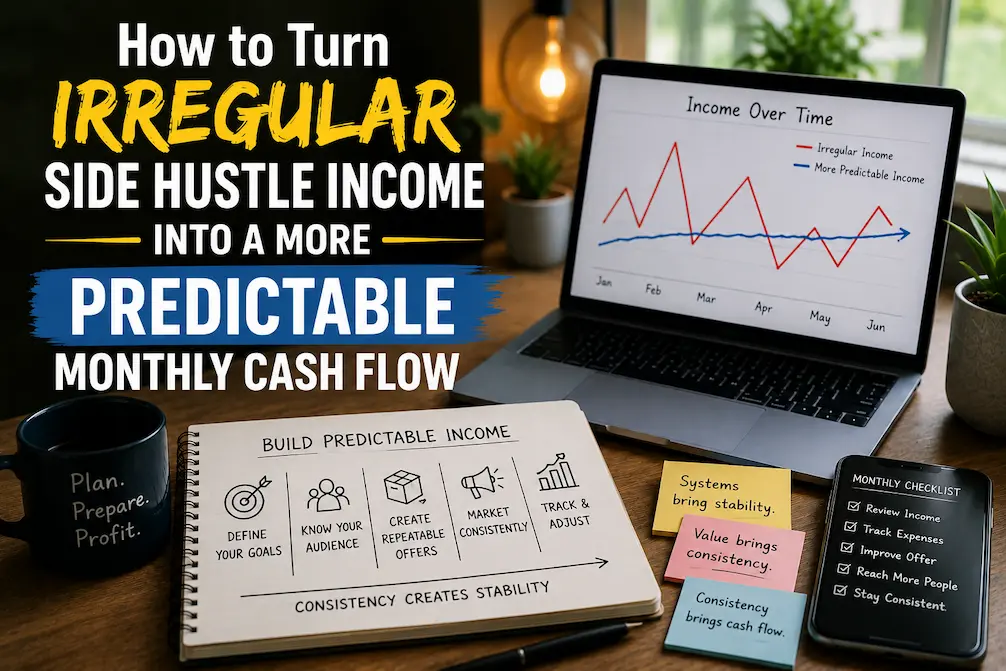

Side gig income is hard to handle because it’s rarely dependable. One month may have many clients and a high payment total, whereas the next may be quieter. That does not mean the side gig is failing. Your budget must account for the income’s timing change from a regular paycheck.
The idea is not to turn irregular income into a fixed salary. Instead, build a mechanism to stabilize your personal spending even when the side gig’s revenue fluctuates. This usually involves separating corporate income from personal expenditures, setting a realistic baseline, generating a financial buffer, and predetermining how much can go into your household budget.
Avoid Treating Every Payment as Monthly Spending.
One of the biggest issues with irregular side gig income is spending what comes in. A strong month can make it seem like there’s more money for bills, shopping, entertainment, and other goals. When the following month is weaker, maintaining expenditure becomes tough. The issue is when money is spent, not how much is earned.
You should treat side hustle revenue as money that first enters a holding area rather than personal spending budget money. You can then account for business expenses, taxes, upcoming responsibilities, and the amount you plan to transfer to yourself. This separates side gig earnings from home spending.
That distinction is crucial when the side gig costs money. A $1,000 client payment doesn’t guarantee $1,000 for personal expenditures. That amount may cover supplies, software, transaction fees, transportation, refunds, taxes, and other duties. Viewing the money in phases gives a more accurate view of the side gig’s potential.
Determine Your Monthly Baseline
Look backward rather than forward when determining monthly side hustle income. Look at several months of actual income to see what the side gig makes after expenses. tied pick the best month or create an optimistic average. A number that feels sustainable without relying on a lucky streak is ideal.
Your side gig may net you $350 in one month, $700 in another, $500 in another, and $250 in a calmer month. An average can be informative, but it shouldn’t constitute your monthly spending limit. If revenue varies greatly, adopting the average as a guarantee could leave you short during weaker periods.
A more conservative foundation may suit personal budgeting. You may allocate a percentage of your typical side-hustle revenue to recurring household spending while using stronger months to build the buffer or fund specific goals. How reliable the job is, how important the income is to your household, and how financially flexible you are determine the amount.
Use a Range Instead of a Perfect Number
Thinking in ranges helps explain irregular revenue. Instead of saying, “My side hustle makes $600 every month,” you might mention $300–$700. That range makes planning more practical instantly.
Your personal budget can then be kept low rather than hopeful. Should the side gig generate more than that baseline, the difference need not be spent. It can be used for future months, taxes, company expenditures, savings, or other purposes.
The budget is more resilient with this technique. Because you expected variety, a weaker month is less disruptive. The baseline is not meant to anticipate the future entirely. It prevents your spending from being based on uncertain revenue.
Create a Side-Hustle Cash Buffer
A cash buffer is one of the most useful tools for smoothing irregular income. Think of it as a reserve that allows you to separate earning periods from spending periods. During stronger months, more money stays in the reserve. During weaker months, an appropriate amount can be transferred from the reserve to maintain your planned personal contribution.
This is different from simply keeping extra money in your main checking account. When everything sits together, a high balance can make it difficult to tell how much is genuinely available for spending. A dedicated savings or holding account can make the distinction clearer, particularly if you are using the side hustle to supplement household income.
There is no universal amount that every side hustler needs to keep in this buffer. Someone with highly predictable client contracts may need less flexibility than someone whose income depends on seasonal demand, one-off projects, or gig platforms. The important point is to build the reserve gradually rather than waiting for a perfect month in which you can save a large amount.
Build the Buffer During Strong Months
A strong month is most useful when it improves your ability to handle the next weak month. Instead of automatically increasing your lifestyle whenever income rises, decide beforehand what happens to income above your normal baseline.
For instance, if you decide that $400 is your normal monthly personal transfer and the side hustle produces substantially more than that after expenses, the excess can remain in the cash buffer. After several stronger months, that reserve can help support the same $400 transfer when the business has a slower period.
This creates a simple form of self-smoothing. Customers do not have to pay you the same amount every month because your personal budget is no longer directly connected to the exact timing of each payment. You are using accumulated cash to reduce the effect of short-term fluctuations.
Pay Yourself on a Schedule
If every customer payment immediately moves into your personal checking account, your household finances will naturally rise and fall with the side hustle. One practical alternative is to establish a regular transfer schedule. Instead of transferring money whenever a payment arrives, you can move a planned amount at a consistent time, assuming the side hustle has enough available cash after its obligations are covered.
The schedule might be monthly, twice a month, or another interval that fits your household budget. The important feature is consistency rather than a particular frequency. Your personal finances begin to interact with a predictable transfer instead of a stream of unpredictable customer payments.
This does not mean you should blindly transfer the same amount regardless of circumstances. Review the side hustle’s available cash and upcoming expenses before making the transfer. If revenue falls significantly or a major business cost is approaching, reducing the transfer can be more responsible than forcing the side hustle to fund an amount it cannot comfortably support.
Separate Business Money From Personal Money
Mixing side hustle revenue with everyday household spending makes irregular income harder to manage. When customer payments, business purchases, grocery spending, and personal bills all pass through the same account, it becomes difficult to determine what the side hustle has actually generated.
Keeping business-related money identifiable can make the process much easier. You can see what has come in, what has gone out, and what is still available before deciding how much to move into personal finances. The exact account structure depends on the type and scale of the activity, but clear separation is valuable even when the side hustle is relatively small.
This separation also helps with recordkeeping. If you eventually need to calculate taxable income, review profitability, identify deductible expenses where applicable, or determine whether the side hustle is worth continuing, having cleaner records can save considerable effort. A side hustle should not require complicated accounting from day one, but it should be organized enough that you can understand its numbers.
Keep Business Expenses Ahead of Personal Transfers
A common mistake is transferring money to yourself based on gross revenue. This can create problems when business expenses arrive later. For example, a freelancer might receive several payments early in the month and transfer most of the money into personal spending. A few weeks later, software renewals, contractor payments, equipment purchases, and other business costs come due.
The better sequence is to account for the side hustle’s obligations first. Revenue comes in, you identify necessary expenses, and you keep aside money that needs to remain available for those expenses. Only then should you determine what is genuinely available for personal use.
This also makes your personal income figure more meaningful. If you consistently transfer money only after business obligations are accounted for, your household budget is less likely to depend on money that was never truly available to spend. That distinction becomes increasingly important as the side hustle grows.
Plan for Taxes Before They Become a Problem
Tax obligations can complicate the idea of predictable side-hustle income because the money you receive may not have had the same withholding treatment as a traditional paycheck. The rules depend on the country, type of activity, business structure, total income, and other circumstances, so there is no single percentage that every side hustler should automatically set aside.
For someone operating in the United States, self-employment and income-tax considerations can apply to qualifying business income, and estimated-tax requirements may apply in some situations. The correct amount depends on the individual’s broader tax circumstances rather than simply taking a fixed percentage of every payment.
The practical lesson is straightforward: do not build your personal monthly spending plan around money that may later be needed for taxes. Keep a separate amount identifiable for tax obligations when appropriate, and review your situation as the side hustle changes. If the income becomes substantial or the tax rules are difficult to interpret, professional tax advice can be worthwhile.
Use Strong Months for Future Stability
One of the most powerful changes you can make is to stop viewing a high-income month as permission to permanently increase your spending. Higher income is useful, but irregular income becomes much easier to manage when strong periods strengthen the months ahead.
Suppose your side hustle has a particularly successful month because you completed several projects at once. Rather than immediately treating the entire surplus as normal income, you might use part of it to replenish your cash buffer, cover upcoming business costs, reserve money for taxes, or work toward a specific financial goal. That allows the unusually strong month to continue benefiting you after it ends.
This does not mean you can never enjoy the money. A side hustle can have personal goals attached to it, and spending some of the surplus can be perfectly reasonable. The important distinction is between a deliberate use of extra income and allowing a temporary increase in revenue to create permanent monthly obligations.
Give Extra Income a Job Before It Arrives
A simple allocation system can make strong months easier to manage. Rather than deciding what to do with extra money after it reaches your account, establish categories in advance.
For example, after you account for business expenses, you can direct any additional side-hustle money toward:
| Purpose | Why it matters |
|---|---|
| Cash-flow buffer | Helps cover weaker future months |
| Tax reserve | Keeps potential tax money separate |
| Business costs | Funds equipment, software, supplies, or other needs |
| Financial goals | Supports savings or debt-reduction goals |
| Personal spending | Allows some reward without raising recurring costs |
The percentages do not need to be identical every month. In fact, forcing every side hustle into a rigid formula can make the system harder to use. The value comes from intentionally deciding where surplus money should go, rather than allowing the entire amount to blend into everyday spending.
Make Your Regular Bills Depend Less on the Side Hustle
If your rent, mortgage, electricity, insurance, groceries, and other essentials require the side hustle to perform well every month, the budget may be too risky. A side gig can boost a household income without requiring expenses that cannot be cut when work slows down.
Supporting recurrent necessary costs with predictable revenue or financial reserves makes management easier. Side-hustle income can be utilized for flexible goals like extra savings, discretionary spending, scheduled purchases, or expedited debt repayment.
This does not mean everyone can separate side-hustle revenue from vital expenses. Variable income is essential for some households. In that case, the cash-flow buffer is even more crucial because it bridges higher and lower earnings periods.
Review the System Instead of Expecting Perfection
Your side gig may evolve. You may attract repeat customers, lose a large client, raise rates, cut hours, add a service, or undergo seasonal adjustments. A cash-flow arrangement that worked six months ago may no longer work.
Check figures occasionally and compare to baseline. A more consistent side gig may boost your personal finance transfer. Lowering the transfer and rebuilding the buffer may improve if revenue is less dependable.
We don’t want a sophisticated financial system that needs regular supervision. Creating a routine makes irregular revenue simpler to handle. A monthly check of revenue, expenses, cash, upcoming obligations, and personal transfers can often indicate system health.
A Better View of Irregular Income
Side-hustle earnings are not needed for predictable personal cash flow. It’s important to separate the two so a weak earning month doesn’t affect home budgets.
The approach is simple: determine what the side gig generates after expenses, set a cautious personal baseline, build a cash buffer, separate business and personal money, account for taxes and forthcoming commitments, and arrange regular transfers to your family. Instead of automatically increasing spending, strong months might help bad months.
A side gig is always unpredictable unless it generates recurring income. We’re not trying to eradicate uncertainty. Manage that uncertainty so your daily financial decisions are based on a realistic amount of money, not what came in this month.
Ethan Walker is a personal finance writer who focuses on helping beginners understand money simply and practically. He writes about budgeting, saving money, financial literacy, and side hustles with the goal of making financial education easier and more approachable. His content is designed to help readers build better financial habits and make smarter everyday money decisions.