
Building credit can feel like a catch-22 when you have never had a credit card. Lenders want to see a history of responsible borrowing, but establishing that history can be difficult when you do not already have a credit account.
The good news is that a credit card is not the only possible way to establish credit history. Depending on your circumstances, a credit-builder loan, certain installment loans, or another financial product that reports payments to the major credit reporting companies may help create a record of responsible borrowing. Some rent-reporting services may also report eligible payments, although rent reporting is not automatic and the details depend on the provider.
The important distinction is that using a debit card, paying with cash, or simply having money in a bank account generally does not create the borrowing history used by traditional credit-scoring models. Building credit without a credit card therefore means finding a suitable form of reported credit activity and managing it responsibly over time. The Consumer Financial Protection Bureau specifically identifies credit-builder loans and certain other credit products as possible ways to establish or rebuild a credit history.
What It Means to Have No Credit History
Having no credit history is different from having bad credit.
A person with no credit history may simply have little or no information about borrowing and repayment in their credit files. A person with bad credit, on the other hand, may have a history that includes late payments, defaults, collections, or other negative information.
That distinction matters because the solution is different. Someone starting from scratch generally needs to establish a track record. Someone with damaged credit may need to address existing problems while rebuilding that record.
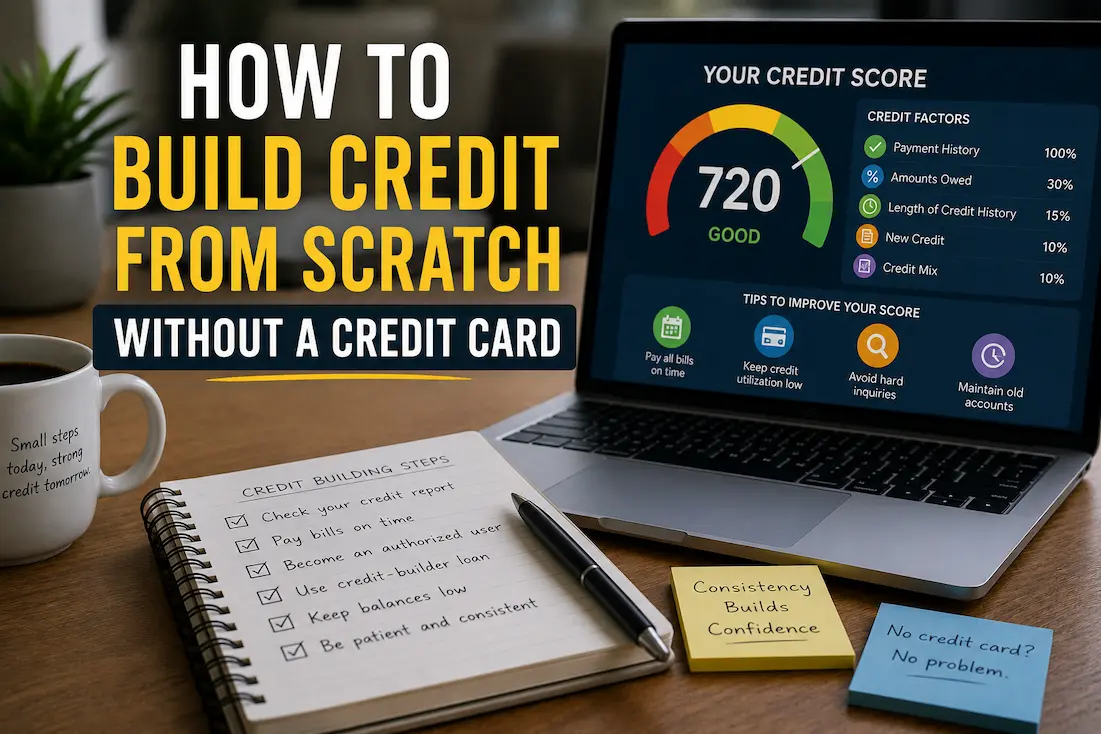
There is also no single universal “credit score.” Credit scores are calculated using information from credit reports, and different scoring models can evaluate that information differently. For example, FICO scoring models consider categories including payment history, amounts owed, length of credit history, new credit, and credit mix. The relative importance of these factors can also vary by individual credit profile.
Why You Can Build Credit Without a Credit Card
A credit card is one form of revolving credit, but it is not the only type of account that can appear on a credit report.
Installment loans are another example. With an installment loan, a borrower generally receives financing and repays it through scheduled payments over a defined period. If the lender reports the account and its payment history to the credit reporting companies, those payments can become part of the borrower’s credit history.
A credit-builder loan is a product specifically designed around this idea. The CFPB explains that these loans commonly place borrowed funds into a savings account while the borrower makes payments. After the loan term, the accumulated funds are made available to the borrower, subject to the product’s terms, interest, and fees.
The key point is not simply having an account. The account needs to generate information that is actually reported to the credit reporting companies.
Start by Checking Whether You Already Have a Credit File
Before applying for a new product, find out whether you already have a credit report.
You might have a credit history without realizing it. An account opened in the past, an installment loan, or another reported obligation may already appear in your file. Starting with a credit report prevents you from applying for unnecessary products simply because you assume you have no credit.
For U.S. consumers, AnnualCreditReport.com is the federally authorized source for obtaining credit reports from Equifax, Experian, and TransUnion. The site currently allows consumers to request free weekly reports from each of the three major credit reporting companies. Checking your own report does not affect your credit score.
When reviewing your reports, look for accounts you recognize, accounts you do not recognize, incorrect personal information, and payment information that does not appear accurate.
If you discover inaccurate information, dispute it with the appropriate credit reporting company and, where appropriate, the company that supplied the information.
Credit-Builder Loans Can Be One Option
A credit-builder loan is designed differently from a conventional personal loan.
Instead of receiving the loan proceeds immediately to spend, the lender generally places the funds into a restricted savings account. You then make scheduled payments. If the lender reports those payments to the major credit reporting companies, your payment history can become part of your credit file.
At the end of the repayment period, the lender generally releases the money to you according to the agreement.
| Feature | Credit-builder loan |
|---|---|
| Money available to spend immediately | Usually no |
| Regular payments | Yes |
| Credit reporting | Depends on the lender, so verify before applying |
| Savings component | Common |
| Interest and fees | May apply |
| Main purpose | Build credit history and potentially savings |
A credit-builder loan is not automatically a good choice for everyone. If the monthly payment would strain your budget, taking the loan simply to create a credit history may not make sense.
Before signing up, check the total cost, payment amount, repayment period, reporting practices, and what happens if you pay the loan early.
Rent Reporting May Help in Some Situations
Rent is another area worth investigating, particularly for people who already make regular housing payments but have little traditional credit history.
Some services allow eligible rental payments to be reported to credit reporting companies. However, renters should not assume that paying rent automatically builds credit.
Whether rent is reported can depend on the landlord, property manager, reporting service, credit bureau, and specific arrangement. Some services may charge fees, and the information reported may vary.
The CFPB has noted that rent and other recurring payments can potentially be reported through certain services, but consumers should check the fees and conditions before enrolling.
This makes rent reporting something to research carefully, rather than a guaranteed credit-building method.
An Installment Loan Can Create Credit History, but Don’t Borrow Unnecessarily
A legitimate installment loan that reports payment activity can contribute to a credit history. Examples can include certain auto loans, student loans, or other qualifying loans.
But this does not mean you should borrow money simply because you want a credit score.
Taking on an unnecessary loan creates an actual financial obligation. You may have to pay interest, fees, and principal, and missing payments can create problems rather than solve them.
The better approach is to separate two questions:
Do I genuinely need this financing?
and
If I use it, will the account be reported to the credit reporting companies?
If you genuinely need a loan, responsible repayment may help establish a credit history. If you do not need to borrow, there is usually little reason to create debt merely for the sake of having another account.
Becoming an Authorized User Can Be Another Possibility
In some circumstances, becoming an authorized user on another person’s credit card may allow information from that account to appear on your credit report.
This can be useful when a trusted family member or another person adds you to an account that they manage responsibly. However, the effect depends on the card issuer, the credit reporting practices involved, and the scoring model being used.
It is also important to understand that an authorized-user arrangement does not give you the same responsibility or control as being the primary account holder.
If the account has high balances or a history of missed payments, the information associated with it may not be helpful. Anyone considering this arrangement should understand the account’s history and confirm how the issuer handles authorized-user reporting before relying on it as a credit-building strategy.
Focus on Payment History Once an Account Exists
Getting your first reported account is only the beginning.
Payment history is one of the most important categories used in FICO scoring. FICO identifies payment history as accounting for 35% of a general FICO Score calculation, although the importance of individual factors can vary between consumers and scoring models.
That makes consistent payments more important than trying to accumulate as many accounts as possible.
A simple system can help:
- Put due dates on a calendar.
- Set up payment reminders.
- Consider automatic payments when appropriate.
- Keep enough money available to cover scheduled payments.
- Review account statements regularly.
- Contact the lender promptly if you anticipate difficulty making a payment.
Automatic payments can reduce the risk of forgetting a due date, but they should not replace checking your account balance and statements.
You Do Not Need to Carry Debt to Build Good Credit
One of the most persistent credit myths is that you need to maintain a balance or pay interest to build a good credit history.
That is not necessary.
If you have a credit account, making payments as agreed is what matters. For revolving credit, paying the balance in full can help you avoid finance charges while still allowing the account’s activity to be reported.
The CFPB specifically notes that consumers do not need to carry a balance on a credit card to build a good credit score.
The same general principle is useful when thinking about credit-building strategies without a card: the objective is to demonstrate responsible management of credit, not to pay unnecessary interest.
Keep New Applications Under Control
When people discover they need credit history, it can be tempting to apply for several products at once.
That approach can create unnecessary problems.
Applications for credit can result in inquiries, and opening several new accounts over a short period can affect credit profiles. FICO also considers recent credit activity when calculating scores, and opening multiple accounts in a short period can be more significant for people with limited credit histories.
Instead of applying everywhere, compare your options first.
Look at:
- Whether the account reports to the major credit reporting companies
- Interest rates
- Fees
- Required deposits
- Monthly payments
- Early-payment or early-closure rules
- Eligibility requirements
- Whether the product actually fits your budget
One appropriate account that you can manage comfortably is generally more useful than several accounts you opened simply because you wanted to create credit quickly.
Give Your Credit History Time to Develop
Building credit is not an overnight process.
A new account needs time to generate a meaningful record of payments. FICO notes that, for a valid FICO Score, a credit report generally needs at least one account that has been open for six months or more and at least one account reported within the previous six months.
That does not mean everyone will receive the same score after six months. Credit-scoring models differ, lenders use different criteria, and individual credit files contain different information.
The practical lesson is simpler: consistency matters more than speed.
Someone who makes manageable payments on time for a longer period is building a more useful record than someone who opens several accounts quickly and struggles to manage them.
Monitor Your Credit Reports as You Build
Credit building should include periodic monitoring.
Checking your credit reports can help you confirm that accounts are being reported correctly and identify unfamiliar activity. It can also reveal errors that need to be disputed.
For U.S. consumers, AnnualCreditReport.com provides access to reports from the three major nationwide credit reporting companies. The official site states that requesting your own reports does not affect your credit scores.
Monitoring is particularly useful when you are establishing credit for the first time because you are learning what information is actually appearing in your reports.
Do not assume that every payment you make will appear. Reporting practices vary by account and provider.
What Usually Does Not Build Traditional Credit
Some everyday financial behaviors are responsible and useful but generally do not create the same type of credit history as reported borrowing.
For example, paying with cash or using a debit card normally does not demonstrate repayment of borrowed money. Prepaid cards generally work similarly because you are spending money that you have already loaded onto the card.
The CFPB specifically notes that cash, debit cards, prepaid cards, and certain payday loans typically do not establish credit history through reporting to the nationwide credit reporting companies.
This does not make these products undesirable A debit card, for example, can be an effective way to control spending and avoid borrowing. It simply means you should not expect ordinary debit-card purchases to build the same credit history as a reported credit account.
A Practical Starting Plan
If you have no credit card and want to establish credit, you do not need to rush into a complicated strategy.
A reasonable starting process is:
1. Check your existing credit reports.
Find out whether you already have a file and whether anything is inaccurate.
2. Decide whether you actually need a credit-building product.
Do not borrow money simply because you think you need a score.
3. Research products that report payments.
Credit-builder loans and certain other installment products may be options, depending on your circumstances.
4. Compare the total cost.
Look beyond the advertised monthly payment and check interest, fees, deposits, and other conditions.
5. Make every payment on time.
Set reminders or automatic payments if they fit your situation.
6. Keep the account manageable.
A credit-building strategy should not interfere with rent, food, utilities, emergency savings, or other essential obligations.
7. Monitor your credit reports.
Confirm that the account is being reported as expected and look for errors or unfamiliar activity.
8. Give the process time.
A longer record of responsible management is more meaningful than trying to create several accounts quickly.
Common Mistakes to Avoid
Building credit without a credit card is possible, but some approaches can do more harm than good.
Borrowing money you do not need
A loan creates a real financial obligation. The potential credit-building benefit should not be the only reason you take on debt.
Choosing a product without checking reporting practices
A financial product does not automatically build credit. Ask which credit reporting companies receive payment information and whether reporting is part of the product.
Paying unnecessary fees
Some credit-building products charge application fees, monthly fees, interest, or other costs. Compare the total cost before signing up.
Applying for multiple accounts at once
More accounts do not automatically mean better credit. Several applications in a short period can create unnecessary inquiries and new-account activity.
Assuming every bill builds credit
Paying rent, utilities, phone bills, or other household expenses responsibly is important, but those payments are not necessarily reported to the credit reporting companies.
Expecting a specific score by a specific date
Credit scores depend on the information in an individual’s credit file and the scoring model being used. Even similar actions can produce different results for different people. FICO specifically cautions that the effect of a credit action depends on the starting credit profile.
Building Credit Is About Creating a Reliable Record
You do not need a credit card simply because you want to establish credit. What you need is a form of credit activity that is reported to the relevant credit reporting companies and that you can manage responsibly.
For some people, that may mean a credit-builder loan. For others, an existing installment loan, a properly reported rental payment, or another suitable account may provide the opportunity to establish a credit history.
The safest approach is not to chase a particular score as quickly as possible. Start by understanding your current credit file, choose a product only when it makes sense for your financial situation, verify that payments are reported, and make those payments consistently.
Over time, responsible credit management can create the history lenders use when evaluating future applications. There is no shortcut that replaces that history, and taking on unnecessary debt simply to create a score can defeat the purpose of building healthier finances in the first place.
This article provides general financial education and focuses on the U.S. credit-reporting system. Credit reporting practices, scoring models, lender requirements, and financial products can vary. Before opening an account or taking out a loan, review the current terms, costs, and reporting practices of the provider.
Ethan Walker is a personal finance writer who focuses on helping beginners understand money simply and practically. He writes about budgeting, saving money, financial literacy, and side hustles with the goal of making financial education easier and more approachable. His content is designed to help readers build better financial habits and make smarter everyday money decisions.