
Banks are a familiar part of everyday life. People use them to receive paychecks, pay bills, save money, transfer funds, and borrow for major purchases. Businesses use banks for working capital, payments, credit lines, and other financial services. Yet the way a bank earns money is less obvious than the services customers see on the surface.
A bank is not simply a place that stores money and then lends the same money to someone else. Banks manage deposits and other sources of funding, make loans and investments, provide payment and financial services, and balance the income from those activities against operating costs, funding costs, credit losses, and other risks. In the United States, commercial banks are financial intermediaries that raise funds through deposits and other sources and use those funds for activities such as lending and investing in securities.
Understanding this basic model makes it easier to understand why banks charge interest, pay interest on some accounts, collect certain fees, and pay close attention to credit risk and interest rates.
What a Bank Actually Does
At its simplest, a bank connects different parts of the financial system. One customer may want somewhere to keep money and make payments, while another may need financing to buy a home, purchase equipment, cover business expenses, or handle another legitimate need for credit.
The bank provides the infrastructure that allows these activities to happen. It maintains accounts, processes payments, evaluates borrowers, manages deposits and other funding, holds financial assets, and handles the operational work involved in serving customers. Banks also operate under regulatory and supervisory requirements designed to promote the safety and soundness of the banking system.
The important point is that a bank has both income and expenses. Earning interest on a loan does not mean the entire amount is profit. The bank may have to pay interest to depositors or other funding providers, cover employee and technology costs, maintain branches and payment systems, absorb losses from loans that do not perform as expected, and meet other operating expenses.
That difference between revenue and the many costs of running a bank is what ultimately matters when considering profitability.
Where Banks Get the Money They Use
Deposits are an important source of funding for many banks. Checking accounts, savings accounts, certificates of deposit, and other deposit products create liabilities for the bank because the bank has an obligation to customers according to the terms of their accounts.
Deposits are not the only source of funding, however. Banks can also use other forms of borrowing and funding arrangements. The Federal Reserve’s financial accounts describe U.S.-chartered depository institutions as raising funds through demand and time deposits as well as sources such as federal funds purchases, repurchase agreements, borrowing from other lending institutions, and other arrangements.
This distinction matters because it is misleading to imagine that every dollar deposited into a checking account is individually matched with a particular loan. Banking is more complicated than that. A bank manages its overall balance sheet, including its assets, liabilities, capital, liquidity, and funding needs.
A simplified view
| Bank activity | What it represents |
|---|---|
| Customer deposits | A source of funding and a liability for the bank |
| Loans to customers | An asset that can generate interest income |
| Securities and other assets | Investments that may generate income |
| Borrowed funds | Additional sources of funding |
| Bank capital | A financial cushion that helps absorb losses |
| Operating expenses | Costs of running the institution |
This is a simplified picture rather than a complete bank balance sheet, but it helps explain why a bank’s business cannot be reduced to deposits and loans alone.
How Banks Make Money From Loans
Lending is one of the most important ways banks can generate income.
When a bank provides a mortgage, auto loan, personal loan, business loan, or another form of credit, the borrower generally pays interest according to the terms of the agreement. The bank records income associated with the loan, while also considering the costs and risks involved in providing that credit.
For example, imagine a bank makes a loan at an interest rate that is higher than the rate it pays on some of its funding. That difference can contribute to the bank’s earnings. But the difference is not automatically pure profit because the bank has other expenses and risks to account for.
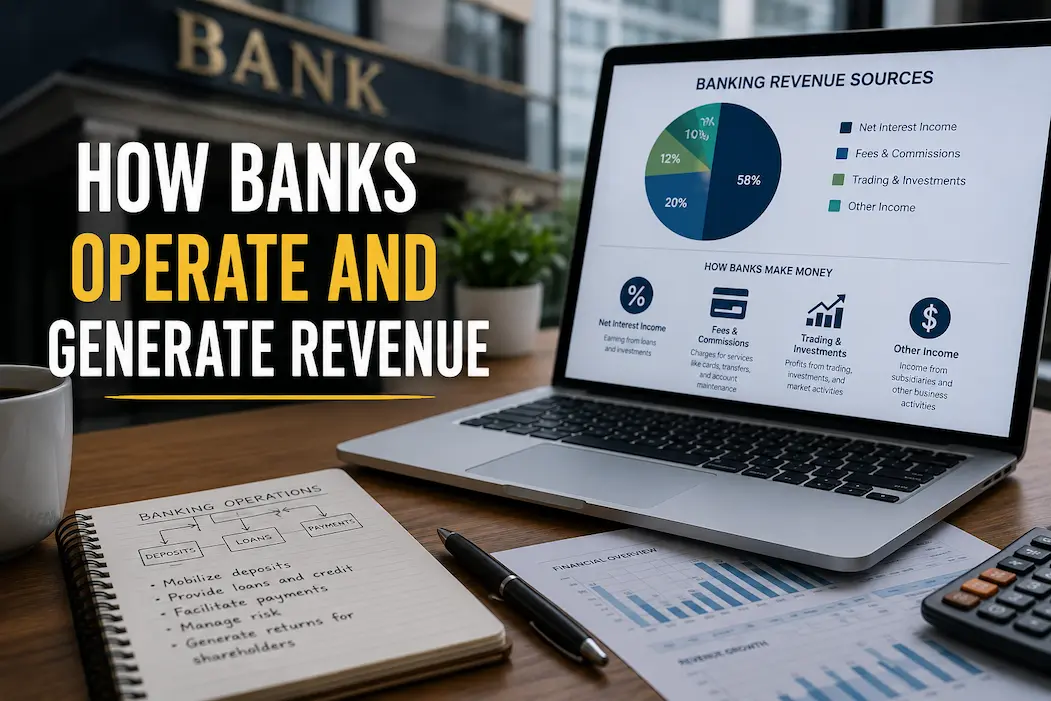
A useful concept here is net interest income. In broad terms, it reflects the difference between interest income earned on assets such as loans and securities and interest expense paid on funding sources such as deposits and borrowings.
The size of that difference can change when interest rates move.
If lending rates rise but the bank’s funding costs remain relatively stable, interest income may increase faster than interest expense. On the other hand, if banks have to pay substantially more to attract or retain deposits, their funding costs can rise and reduce the spread between what they earn and what they pay.
Interest rates can therefore affect both sides of a bank’s business. The FDIC has noted that higher rates can allow banks to charge more on loans while also increasing what they may have to pay for deposits, while changing rates can also affect the value of securities held by banks.
Interest Income Is Not the Same as Profit
It is easy to look at a loan’s interest rate and assume that the bank keeps the difference as profit. That is not how bank profitability works.
Consider a simplified example. Suppose a bank earns interest from loans and investments but also pays interest on deposits and other funding. It then has to cover salaries, technology, offices, payment infrastructure, compliance, servicing, and other operating costs. It also needs to account for the possibility that some borrowers will not repay as expected.
The Federal Reserve’s banking-related financial reporting separates income from operating expenses, the cost of borrowed funds, taxes, and losses or additions to loss reserves.
So when someone asks, “How much does a bank make from a loan?” the more accurate answer is that the loan contributes to the bank’s overall income, but the eventual profit depends on the costs and risks associated with the bank’s broader operation.
Banks Also Earn Money From Fees and Services
Interest is only part of the picture.
Banks may earn noninterest income from various services and activities. Depending on the institution and the products it offers, these can include account-related charges, payment services, card-related activities, investment or wealth-management services, and other financial services.
The exact mix differs from one bank to another. A large commercial bank with extensive business and investment operations can have a very different revenue profile from a smaller institution that focuses primarily on traditional deposits and lending.
Federal Reserve reporting categories show that banking-related income can include interest and fee income, service charges, commissions, and other forms of income rather than coming from lending alone.
This is why comparing banks solely by the interest rate they charge on loans does not provide a complete picture of how they make money.
Why Banks Pay Interest to Depositors
If banks want to earn money from lending, why do they pay customers interest on savings accounts and other deposits?
Because deposits are valuable funding sources, and banks compete for them.
A customer who keeps money in a savings account is providing the bank with a source of funding while receiving interest according to the account’s terms. The bank must consider the cost of that funding when deciding how to price loans and manage its balance sheet.
The relationship is therefore not simply “the bank gives away free money.” The interest paid to depositors is an expense from the bank’s perspective.
This is also why deposit rates can change. When market conditions and competition change, banks may adjust the rates they offer on savings accounts, certificates of deposit, and other deposit products.
For consumers, this is one reason it is worth comparing account terms rather than assuming every bank pays the same rate.
The Role of Credit Risk
Making loans can be profitable, but lending also exposes banks to the possibility that borrowers will fail to repay.
Before approving a loan, banks generally evaluate factors relevant to the borrower’s ability and willingness to repay. Depending on the product, that may involve income, credit history, existing obligations, collateral, business information, or other factors.
Even after a loan is approved, the bank still has to monitor its lending portfolio.
A bank cannot assume that every borrower will make every payment on time. Some loans may become delinquent, require restructuring, or ultimately result in losses. Those potential losses are part of the economics of lending.
This is why a bank’s interest income should never be viewed in isolation. A loan with a high interest rate may also carry greater credit risk, while a lower-risk loan may generate a different return.
Why Banks Invest in Securities
Banks do not necessarily put all available funds into loans.
They can also hold financial securities and other assets. The Federal Reserve’s financial accounts describe U.S.-chartered depository institutions as using their funding for loans as well as investments in securities.
These investments can serve several purposes. They may generate income, provide liquidity, support balance-sheet management, or serve other financial and regulatory functions depending on the asset and the institution.
However, investments can also carry risks. Changes in market interest rates can affect the market value of certain securities, particularly those with longer maturities or greater sensitivity to interest-rate movements.
That is one reason bank management involves much more than simply maximizing the amount of money lent to borrowers.
A Simple Example of the Banking Model
Imagine a hypothetical bank that has a mixture of customer deposits and other funding sources.
It uses its balance sheet to support several activities:
- making mortgages and other consumer loans;
- providing credit to businesses;
- holding certain securities;
- processing payments;
- maintaining customer accounts; and
- providing additional financial services.
The bank earns income from some of these activities. At the same time, it pays interest on certain funding sources and incurs expenses for employees, technology, facilities, regulatory compliance, payment networks, loan servicing, and other operations.
It also has to prepare for credit losses and other financial risks.
The bank’s final profit is therefore the result of income minus the costs and losses required to generate that income.
This simple framework explains why two banks with similar loan volumes can still produce very different financial results.
What Happens When Interest Rates Change?
Interest rates can influence banks in several ways at the same time.
When rates rise, banks may be able to charge more on newly originated loans or loans with variable rates. But depositors may also expect higher rates on their savings, and banks may face higher costs on other forms of funding.
Higher rates can also affect demand for borrowing. A household considering a mortgage or a business considering a new loan may postpone borrowing if financing becomes more expensive.
There can also be effects on the value of securities already held by banks.
This means there is no simple rule that “higher interest rates are always better for banks” or that “lower rates are always better.” The outcome depends on the bank’s balance sheet, loan portfolio, funding structure, pricing, and risk management.
Why Banks Need Capital and Liquidity
Banks operate with financial risks that require safeguards.
Capital provides a cushion against losses. It is different from customer deposits because it represents the bank’s own financial resources rather than money that the bank owes to depositors.
Liquidity is also important. Banks need access to enough readily available funds to meet payment obligations and customer withdrawals as they come due.
These concepts are easy to overlook when looking only at the customer side of banking. From the bank’s perspective, managing liquidity, capital, credit risk, interest-rate exposure, and operational risk is central to remaining financially sound.
U.S. banking regulators and supervisors monitor these types of risks as part of the broader goal of maintaining a safe and sound banking system.
How This Affects Everyday Customers
Understanding the banking model can make ordinary financial decisions easier to evaluate.
For example, when comparing savings accounts, the interest rate is important because it affects what you earn on your balance. When comparing loans, the interest rate and other costs affect what borrowing may cost you. Account fees, minimum-balance requirements, early-withdrawal rules, and other terms can also matter.
The same principle applies to credit cards and other financial products. A product that looks inexpensive at first may have costs elsewhere in its terms.
Rather than asking only, “What rate does this bank advertise?” it is often more useful to ask:
- What will I pay or earn?
- What fees apply?
- How long does the advertised rate last?
- Are there balance or eligibility requirements?
- Can the rate change?
- What happens if I miss a payment or withdraw money early?
- How does this product fit my actual financial needs?
These questions help turn an understanding of the banking business into practical consumer awareness.
Banks Make Money by Managing a Whole Financial System
Banks generate revenue through a combination of lending, investing, payments, fees, and other financial activities. At the same time, they incur funding costs, operating expenses, credit losses, taxes, and other costs.
The most important idea is that bank revenue is not the same thing as bank profit.
A bank may earn substantial interest from loans while also paying interest to depositors, funding its operations, absorbing losses, and maintaining capital and liquidity. Its profitability depends on how successfully it manages those competing factors over time.
For customers, understanding this model provides useful context when choosing a bank or evaluating a financial product. It explains why banks care about deposits, loan pricing, interest rates, credit quality, fees, and risk—and why the best financial decision is usually based on the full terms of a product rather than a single advertised number.
This article is intended for general financial education. Banking products, regulations, fees, and consumer protections can vary by institution and location. Readers should review the current terms of a financial product and consult an appropriately qualified professional when they need advice specific to their circumstances.
Ethan Walker is a personal finance writer who focuses on helping beginners understand money simply and practically. He writes about budgeting, saving money, financial literacy, and side hustles with the goal of making financial education easier and more approachable. His content is designed to help readers build better financial habits and make smarter everyday money decisions.